A logistics company in Mussafah, Abu Dhabi, gave 14 supervisors an AED 1,800 monthly car allowance without any written company car allowance policy. Two years later, a resignation dispute raised a hard question: was that money part of the wage, and did it change the gratuity?
The answer sits where four rule sets meet: labour law, the Wage Protection System, VAT and corporate tax. A perk that looks simple on an offer letter can create deduction limits, audit exposure, and blocked VAT recovery when it is structured loosely.
This guide shows how UAE employers can structure car and travel perks so they stay defensible and easy to administer. It also flags where sources disagree, because good policy design starts with knowing what is still unsettled.
|
Quick Answer Write car and travel perks into the contract as clearly labelled allowances, keep basic wage separate, pay fixed amounts through WPS and document business use. Input VAT is blocked on vehicles available for personal use, and corporate tax deductions need evidence of business purpose. |
What a company car allowance policy must cover
A policy is not the same as a clause in a contract. The contract sets the amount, while the policy sets eligibility, use, costs, records and what happens on exit. Without it, every dispute becomes a fresh negotiation.
At minimum, cover who qualifies, whether the benefit is cash or a vehicle, who pays fuel, Salik, parking and fines, how personal use is treated, and when the benefit can be reviewed or withdrawn. Tie eligibility to grade or role, not individual favour, so pay stays defensible.
Each element should also be written into the employment contract or an addendum. Under the labour law, changes to agreed terms need the employee's written consent, so a perk promised only verbally is hard to enforce or to withdraw.
Car allowance versus company vehicle
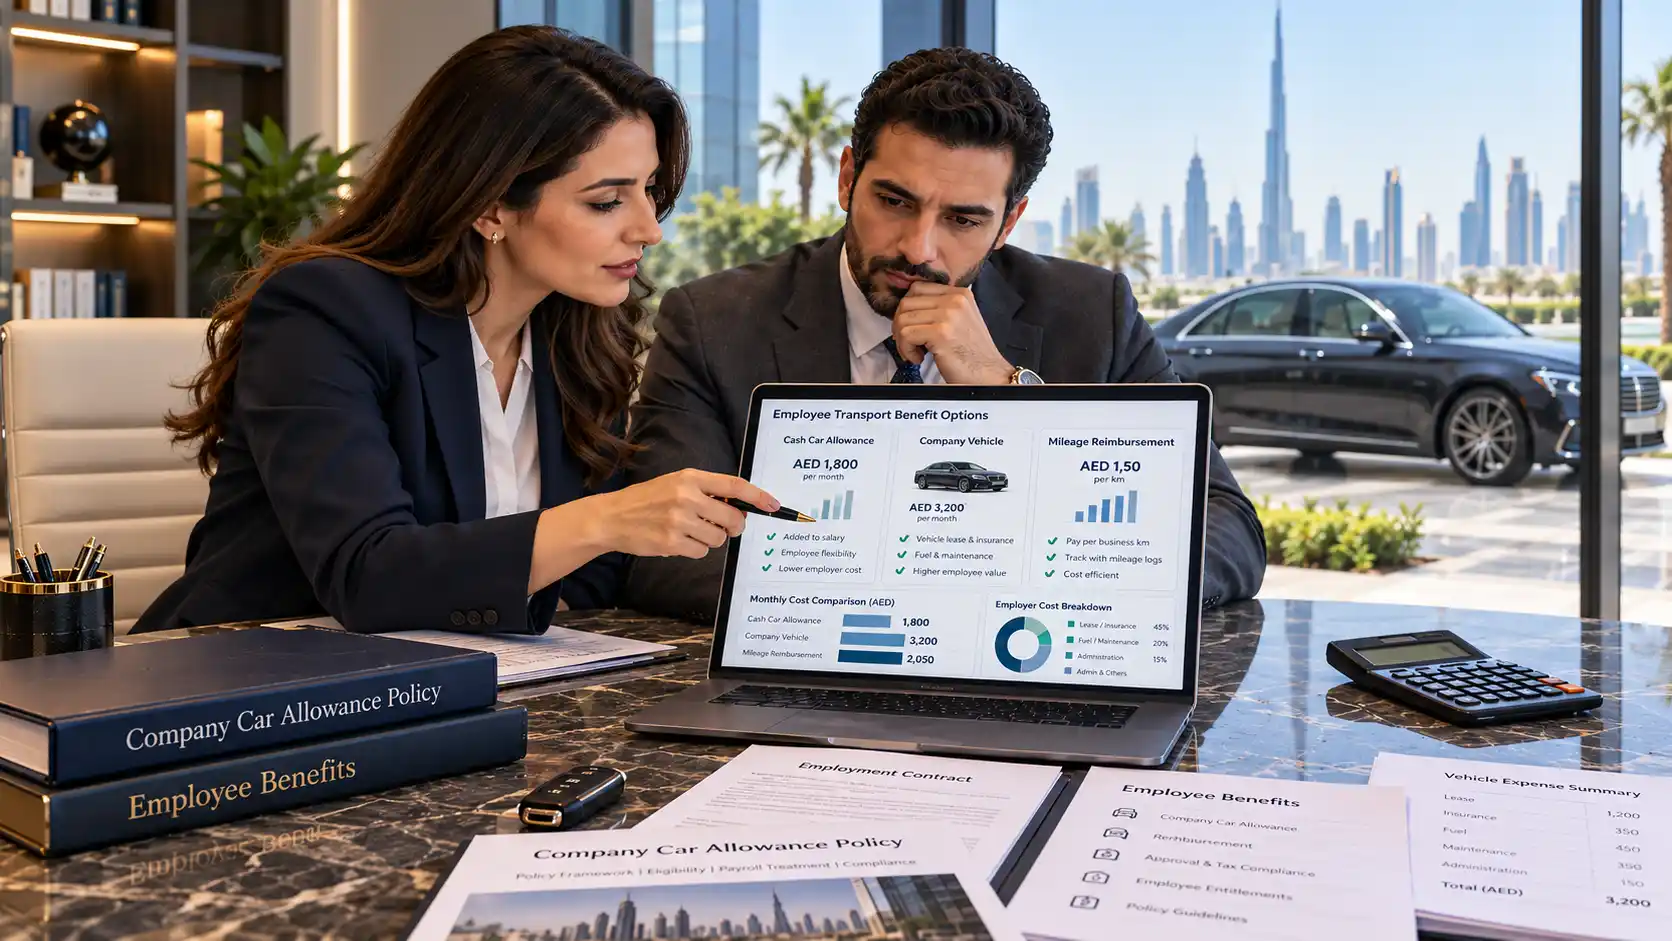
Most UAE employers choose between three structures. Each treats wages, VAT and administration differently, so the right choice depends on headcount, role and how much personal use is realistic.
|
Structure |
Wage and WPS |
VAT |
Corporate tax |
Admin load |
|
Cash car allowance |
Part of total wage, paid via WPS |
No vehicle VAT issue for the employer |
Deductible as an employee cost |
Low |
|
Company-owned or leased car |
Benefit in kind, wage only if the contract says so |
Input VAT blocked if personal use is allowed |
Apportion business and private use |
High |
|
Mileage or expense reimbursement |
Not wage when receipt-backed |
Recoverable on valid tax invoices |
Deductible with business purpose shown |
Medium |
A cash allowance is the easiest to administer and audit. A company vehicle suits roles with real field travel but carries the heaviest tax and record-keeping burden, while reimbursement is cleanest for occasional use.
How car allowances affect gratuity, overtime and WPS
Under Federal Decree-Law No. 33 of 2021, wage covers basic wage plus cash allowances and benefits in kind stated in the contract. Gratuity under Article 51 and overtime are calculated on basic wage only, so a car allowance normally raises neither.
There is one trap. Where a contract states a single gross figure with no breakdown, labour courts have traditionally treated the whole amount as basic. The UAE Government's end-of-service benefits guidance explains the basic wage basis for gratuity.
Cutting basic pay very low to shrink gratuity is also risky, because authorities and courts can challenge artificial structures. Employers can look at flexible benefits packages as a model for balancing cash and non-cash value.
WPS timing under Resolution No. 340 of 2026
From 1 June 2026, Ministerial Resolution No. 340 of 2026 sets a unified due date: the first day of each month for the previous month. Fixed monthly allowances belong in the WPS file with salary, and late payment triggers escalating action by the Ministry of Human Resources and Emiratisation, from warnings to suspended work permits.
Fines, Salik and deductions
Many car disputes start with traffic fines. Article 25 allows deductions only in listed cases and caps total deductions at 50 percent of wage, as the UAE Government wage payment guidance outlines. The new WPS test treats an employee as paid at 85 percent, which in practice limits deductions to about 15 percent.
Agree fines recovery in writing before the vehicle is issued, log each fine with its date and driver, and confirm with counsel which Article 25 category applies before deducting anything.
|
Watch out A fines clause does not override Article 25. If a deduction fits no permitted category or breaches the 50 percent cap, the clause will not protect the employer. |
VAT and corporate tax: the employer-side risk
Employees pay no personal income tax in the UAE, so the main exposure sits with the employer. Under Article 53 of the VAT Executive Regulation, input VAT on motor vehicles made available for personal use is blocked, so a car staff may drive privately usually loses VAT recovery.
Corporate tax works differently. Article 28 of the Corporate Tax Law allows expenditure incurred wholly and exclusively for the business. FTA guidance treats benefits that retain or reward staff as generally deductible, but mixed-use costs may need apportioning, and benefits to owners or directors must reflect market value. The 9 percent rate applies above AED 375,000 of taxable income.
Sources do not fully agree on apportioning mixed-use vehicles, and the rules keep developing. Check current Federal Tax Authority guidance and confirm your position with a registered tax adviser before finalising a vehicle policy.
Building a travel allowance policy UAE employers can defend
Travel perks fall into two groups. Fixed allowances, such as a monthly travel or fuel amount, are wages and belong in the contract and WPS file. Trip costs such as flights, hotels, and per diems are reimbursements tied to evidence.
Set per diem rates by destination band, publish them in the policy, and benchmark the allowance against market pay so it stays competitive. The ReapHR UAE salary guide shows how typical packages split basic pay and allowances.
Require receipts, set approval limits, and state that personal travel booked through the company is not a business expense. That separation also supports the corporate tax deduction.
A practical policy checklist
Before issuing the benefit
Confirm eligibility rules, choose cash or a vehicle, set the amount from market data, and add it to the contract. For vehicles, check insurance, registration in the company name, and driver licence validity.
While it runs
Keep use logs for company vehicles, review amounts every year, and reconcile allowances to the WPS file each month. Small drifts between policy, contract and payroll are easy to fix early and costly to explain later.
Conclusion
A sound company car allowance policy does three things. It separates basic wage from allowances, keeps payments and deductions inside labour law and WPS rules, and records business use for tax purposes.
Start with the contract and a short written policy, confirm the tax position with an adviser, and review it yearly. Clear rules protect the employee's entitlement and the employer's audit position together.
|
Need a policy your team can actually use? ReapHR drafts UAE-compliant company policies and employment documents for employers in Abu Dhabi and across the GCC. |
If you want an expert check on how current perks line up with contracts and payroll, our team runs structured HR audits for UAE employers and can benchmark packages at the same time.
Frequently Asked Questions
Is a car allowance counted as part of basic salary in the UAE?
No. Under Federal Decree-Law No. 33 of 2021, basic wage is the amount paid for work under the contract, while a car or transport allowance sits in total wage. Gratuity, overtime, and leave encashment use basic wage, but a single undivided gross figure can be treated as basic by labour courts.
Can an employer deduct traffic fines from salary?
Only within the deduction categories Article 25 allows, and total deductions cannot exceed 50 percent of wages. Under the WPS resolution effective June 2026, shortfalls beyond 15 percent risk non-compliance. Employers should put a written fines-recovery clause in the vehicle policy and agree it with the employee first.
Is a company car taxable for the employee in the UAE?
There is no personal income tax on employment income, so the employee is not taxed on the benefit. The employer side matters instead: corporate tax deductibility and input VAT, which is blocked on vehicles available for personal use. Owners and directors need market-value support.
Should travel allowances be paid through WPS?
Fixed monthly allowances written into the contract are part of wages and belong in the WPS file. Genuine business travel reimbursements backed by receipts are expense claims, not wages. Per diems should be defined in the policy, with a documented rate, so auditors and the employee see the same logic.
Do employers have to give a car or transport allowance?
No. UAE labour law does not require a car or a transport allowance, so it is a contractual benefit. Once written into the contract, it becomes enforceable, and removing it requires the employee's written consent. Include review and withdrawal terms in the policy from day one.